Your local mortgage brokers in Wellington
From your first home to owning it outright, advice for every move
Wellington mortgage and KiwiSaver advisers helping you buy well, borrow well and make better financial decisions as life changes.
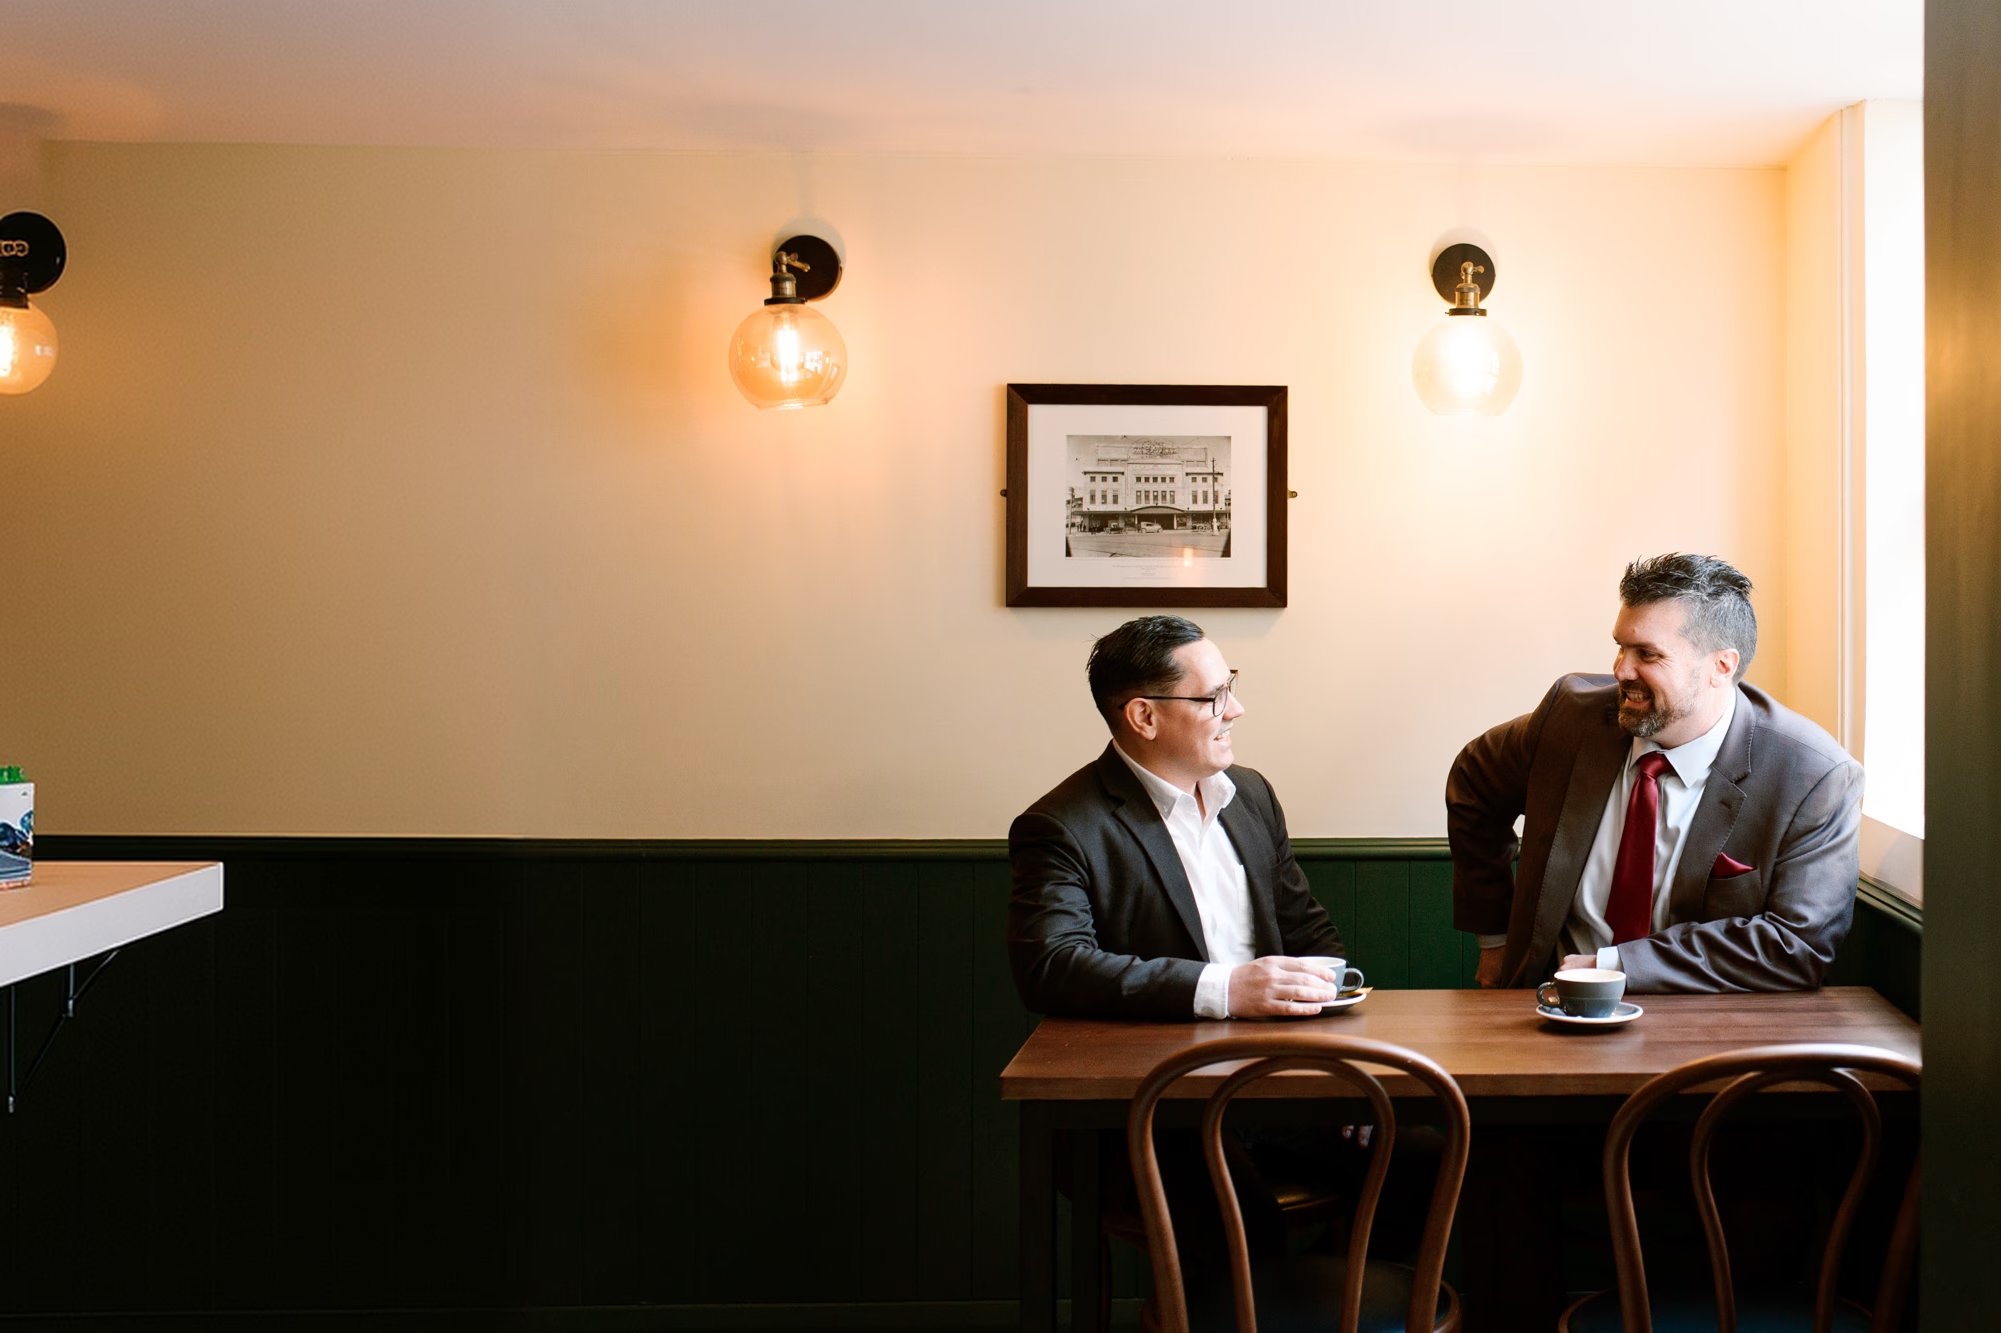
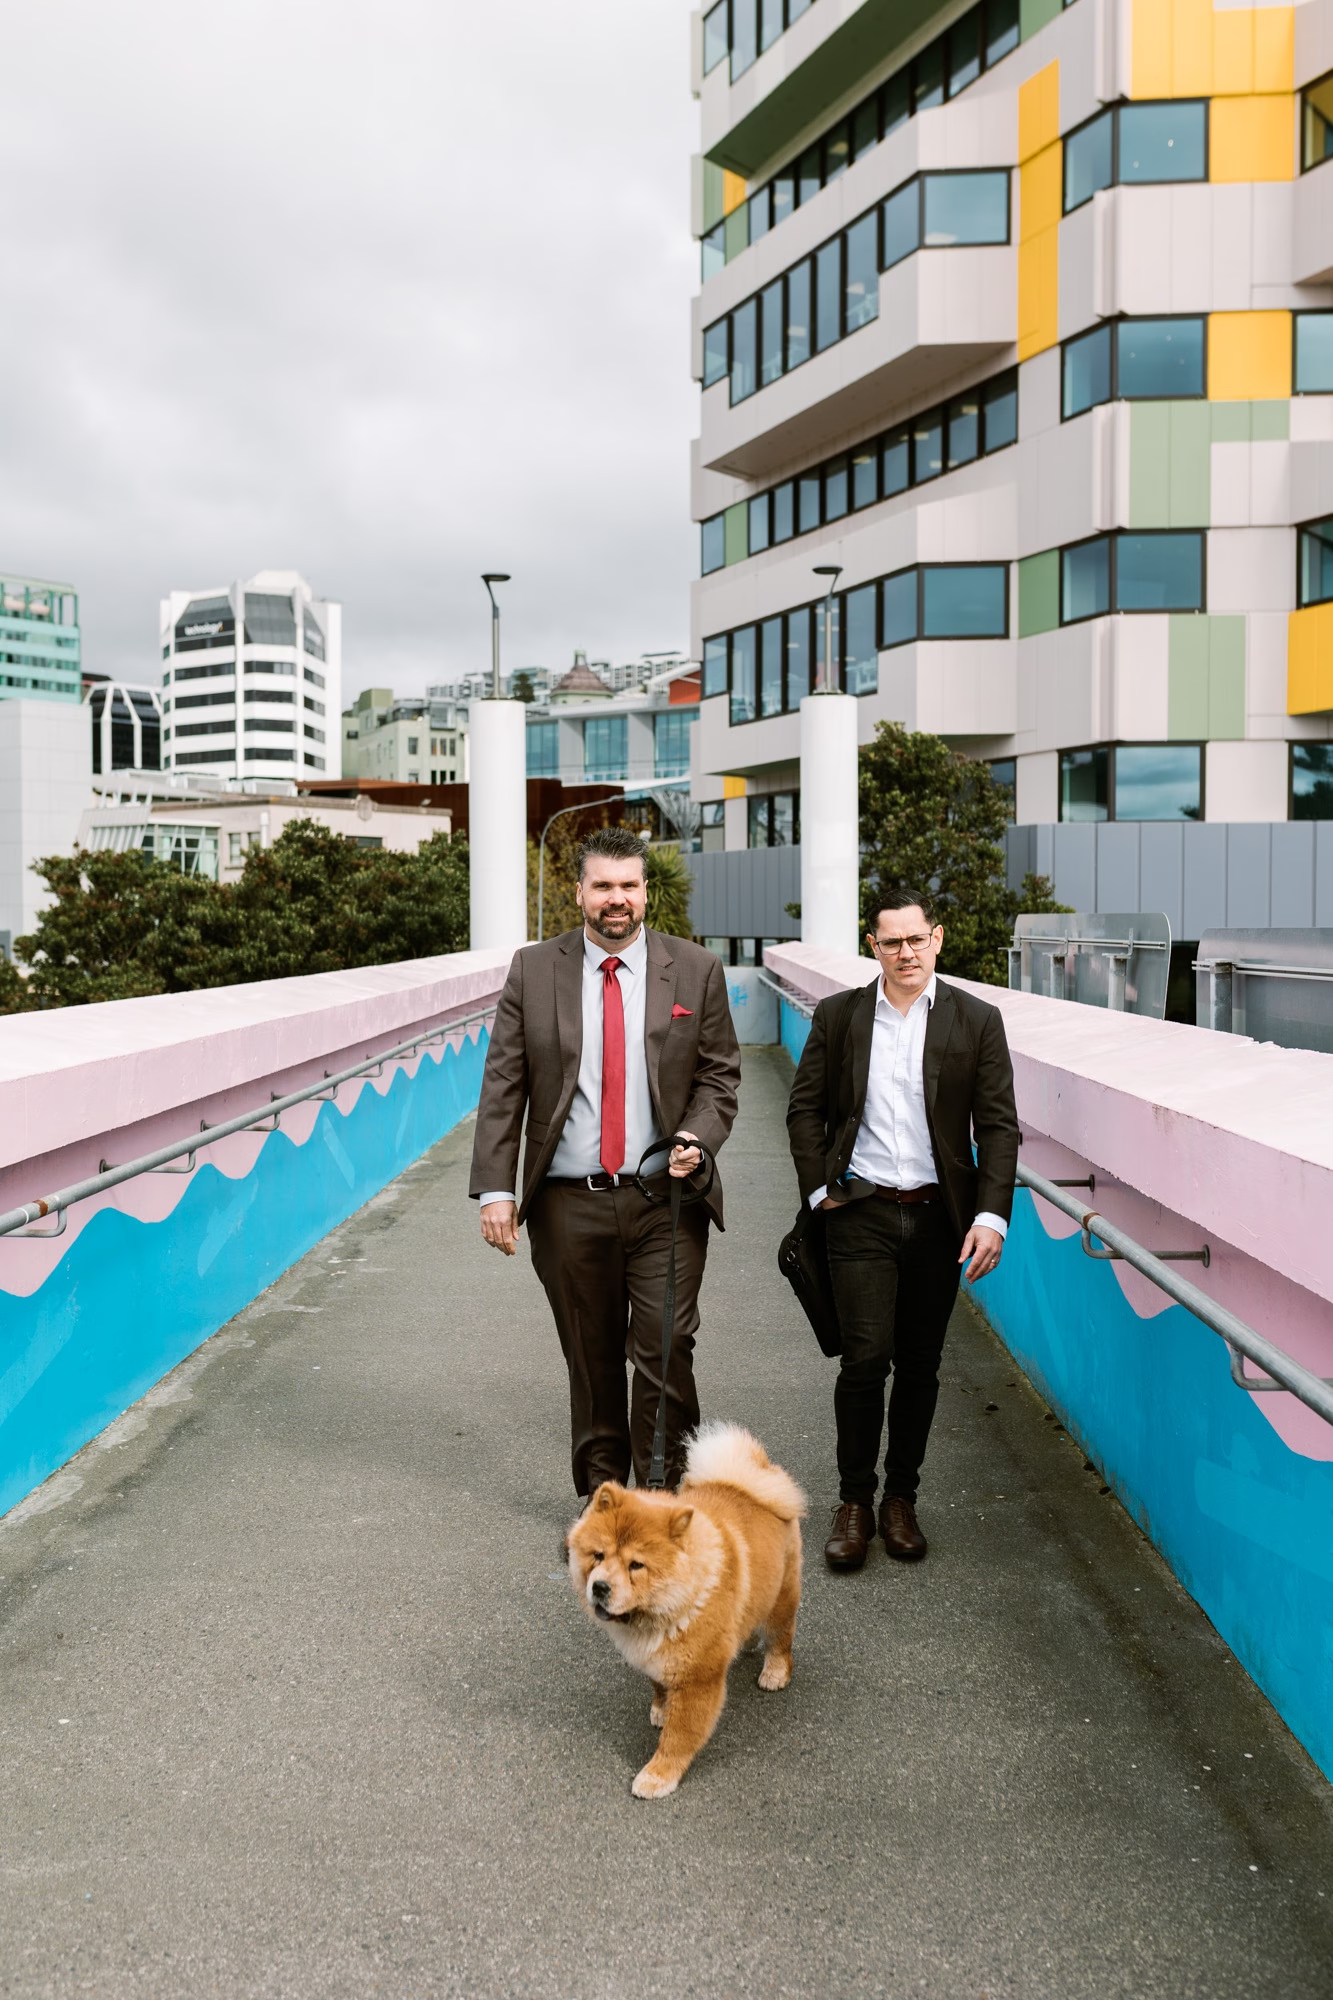
Andrew Perry and Chris Lawrence have been arranging home loans in Wellington since 2016.
We work with more than 20 lenders, including ANZ, ASB, BNZ, Westpac, Kiwibank, TSB Bank, The Co-Operative Bank, and SBS Bank, comparing options across our lender panel rather than giving you one bank’s answer.
First home buyers
Your next home
Getting ahead
Property Investors
KiwiSaver
Mortgage Reviews
Good advice is easier to judge by what happens next.


Lending is a big decision. It doesn’t need to feel like a complicated one.
Banks have different lending policies, rates and appetites – and the lender that works well for one person may not be the right fit for another.
Our job is to understand what you’re trying to achieve, work through the numbers with you and identify the lending options worth considering.
That might mean getting your first home loan approved, using existing equity to make your next move, restructuring a mortgage, buying an investment property or simply checking whether the deal your current bank has offered you is actually a good one.
You’ll deal with real people throughout the process, with clear explanations and no expectation that you already understand the language of lending.
Advice from people who know Wellington.
There is plenty of technology involved in getting a mortgage approved. The advice should still feel human.
Andrew and Chris have worked in mortgage lending since 2016, helping Wellington clients through first homes, property moves, refinancing and investment purchases.
The approach is straightforward: understand the situation properly, explain the options clearly and help you make a well-informed decision without turning the process into something more complicated than it needs to be.
Andrew Perry & Chris Lawrence
Why use a mortgage broker instead of going straight to the bank?
Going directly to a bank can be perfectly sensible when you already know that lender is right for you.
The difficulty is that every bank has its own lending criteria. A “no” from one lender does not automatically mean another will reach the same conclusion – and the lowest advertised rate does not always mean the best overall lending structure.
A mortgage broker can help you:
Understand how much you may be able to borrow
Compare lending options across multiple lenders
Prepare and manage your application
Understand bank terminology and loan conditions
Negotiate with lenders on your behalf
Review how your mortgage is structured
Compare lending options across multiple lenders
And if staying with your existing lender is the most sensible option, we’ll tell you that too.
Recent posts & latest news.
Fixed, floating or split? How to choose when your fixed rate ends
Fixed gives certainty, floating gives flexibility, and a split gives some of each. How to choose the right structure when...
Using your KiwiSaver for your first home: rules, paperwork and timing
Who can withdraw KiwiSaver for a first home, how much you can take out, the paperwork your provider needs, and...
The first home grant is gone. What can first home buyers get now?
The First Home Grant closed in May 2024 and nothing replaced it. Here is what first home buyers can still...
Common questions for mortgage brokers.
Does using a mortgage broker cost me money?
In most standard residential mortgage situations, Lambton is paid a commission by the lender when lending settles, meaning there is generally no direct advice fee to the customer.
There can be situations where fees apply, which should always be explained before you proceed.
Is it better to use a mortgage broker or go directly to a bank?
Going directly to a bank means getting that bank’s answer.
A mortgage broker can assess your situation against the policies and products of multiple lenders. Because lending criteria vary between banks, this can give you more options and help identify which lender is best suited to the application.
How early should I talk to a mortgage broker?
Before you need the mortgage.
For a first home, that could mean months before you intend to buy. For an existing homeowner, it could be when you’re starting to think about selling, renovating or when a fixed rate is approaching expiry.
The earlier conversation lets you find out what needs to happen before deadlines become involved.
Can you guarantee my mortgage will be approved?
No. Lending approval is always ultimately the lender’s decision.
What we can do is assess your circumstances, understand different lenders’ policies and identify where an application is likely to fit before submitting it.
Do you only help people with complicated mortgages?
No.
A common misconception is that mortgage brokers are only useful when a bank has already declined an application.
We help people with straightforward purchases as well as more complicated ones. Sometimes the value is solving a problem. Sometimes it’s simply having someone experienced manage the process and make sure you’re making a good long-term decision.
Don’t see your question here?
Ready to know where you stand?
Whether you are buying your first home, planning your next one, refinancing or investing, start with a straightforward conversation with a Wellington mortgage broker.