KiwiSaver Advice in Wellington
KiwiSaver advice that starts with what the money is actually for
For most people, KiwiSaver has two major jobs
It can help you buy your first home. Then it can help fund your retirement.
Those are two very different goals, often decades apart, which is why simply picking a fund and ignoring it isn’t much of a strategy.
We help Wellington clients review their KiwiSaver alongside the rest of their financial life.
Bought the house? Your KiwiSaver job has changed
This point is often missed. Once you’ve withdrawn your KiwiSaver for a first home, the next major withdrawal may be decades away.
That’s the right time to reconsider:
the fund you’re in
your contribution rate
your tolerance for market ups and downs
how KiwiSaver competes with other demands on cashflow
You may be furnishing a home, renovating, building an emergency fund or trying to pay the mortgage faster. Those are all legitimate uses for household cash.
The job is deciding intentionally rather than letting every contribution and repayment stay on the default setting forever.
Common KiwiSaver mistakes we see
"It's with my bank because I like seeing it in internet banking."
Convenient isn’t necessarily the same as appropriate.
Chasing whichever fund performed best last year
Last year’s winner doesn’t automatically tell you which fund suits your goals or which will perform best next year.
Staying in the wrong type of fund
The appropriate level of risk can change significantly depending on whether you’re buying a house next year or retiring in 30.
Ignoring it altogether
For employed New Zealanders, KiwiSaver represents a meaningful proportion of income being directed towards a long-term investment.
It deserves more than a glance every five years.
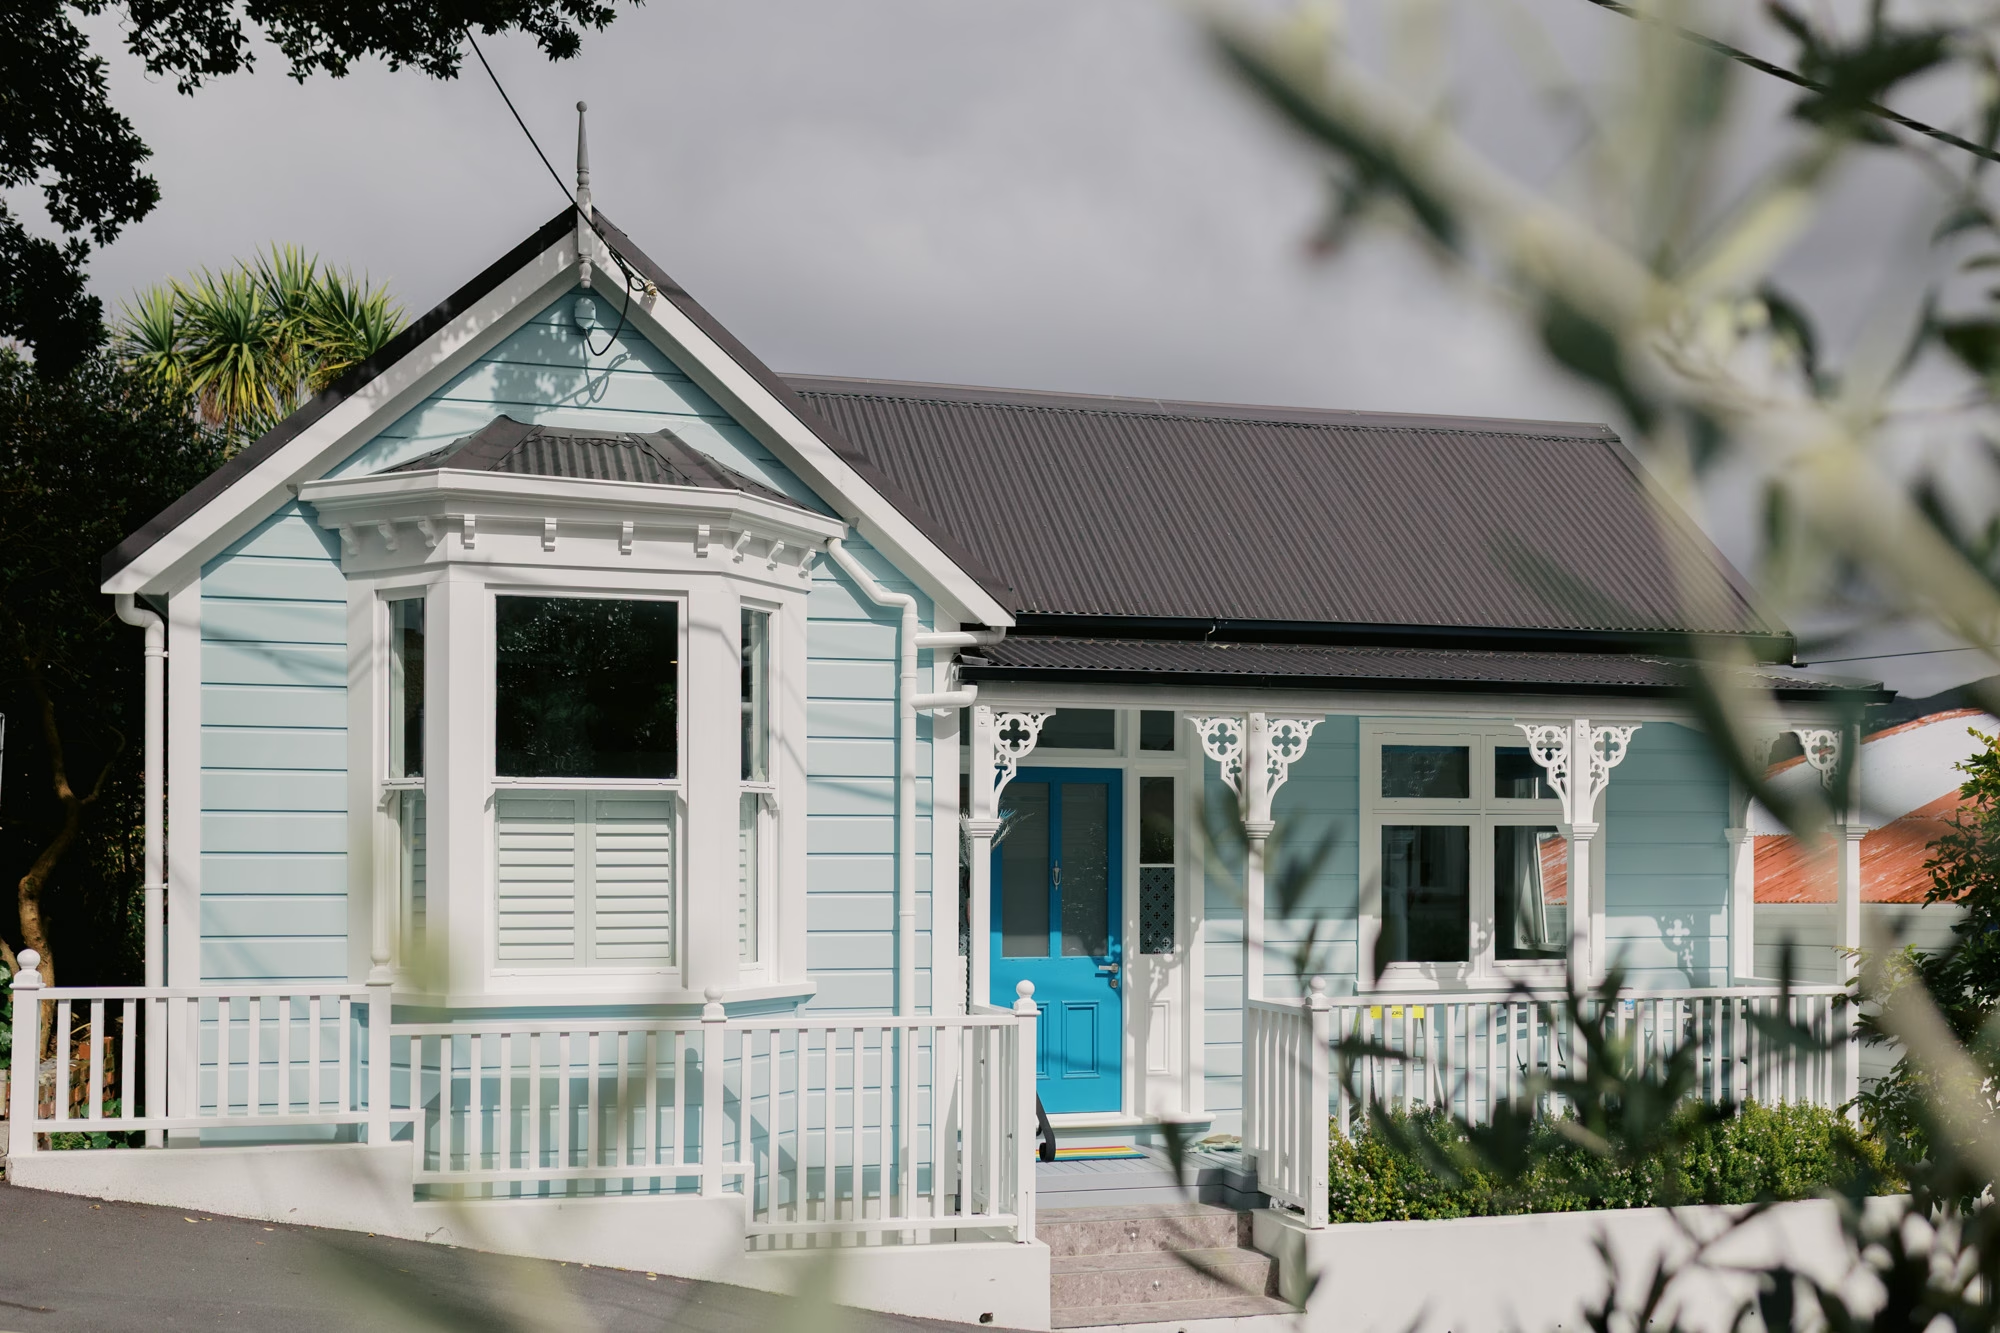
KiwiSaver and your first home
For many first home buyers, KiwiSaver is the main source of their deposit.
That means the timeframe for accessing it matters enormously.
Someone hoping to buy within 12 months shouldn’t necessarily be thinking about investment risk in the same way as someone whose retirement is 30 years away.
We’ll factor KiwiSaver into the first-home planning conversation rather than treating it as a completely separate product.
KiwiSaver providers we work with
Our approved provider panel currently includes:
Any recommendation should be based on your circumstances, goals and risk profile rather than simply selecting one provider from a list.
Frequently asked questions about KiwiSaver
What does a KiwiSaver review involve?
We start with you, rather than last year’s investment return.
We’ll look at:
- what stage of life you’re in
- what you’re using KiwiSaver for
- when you expect to access the money
- your current provider
- your current fund
- contribution rate
- balance
- income
- appetite for investment risk.
Then we look at whether those pieces line up.
What does 'risk' actually mean?
People often get presented with a questionnaire and a label like ‘balanced’ or ‘growth’.
We prefer a more human question:
How far could you watch your KiwiSaver balance fall before you became uncomfortable enough to move it?
Investment markets go backwards sometimes. A suitable fund is one where you understand that possibility and can stay focused on the timeframe rather than panicking and switching after markets have already fallen.
When should you review KiwiSaver?
At least annually, and when something meaningful changes.
That includes:
- starting work
- saving for a first home
- buying your first home
- having children
- receiving a pay rise
- experiencing a reduction in income
- separation
- retirement getting closer
- significant market falls
- changes to KiwiSaver rules
We can review it alongside your annual mortgage review so the two decisions aren’t being made independently of each other.
Don’t see your question here?
Recent posts & latest news.
The first home grant is gone. What can first home buyers get now?
The First Home Grant closed in May 2024 and nothing replaced it. Here is what first home buyers can still...
Using your KiwiSaver for your first home: rules, paperwork and timing
Who can withdraw KiwiSaver for a first home, how much you can take out, the paperwork your provider needs, and...
Fixed, floating or split? How to choose when your fixed rate ends
Fixed gives certainty, floating gives flexibility, and a split gives some of each. How to choose the right structure when...
Give your KiwiSaver an actual job
Whether that job is your first-home deposit or retirement 30 years from now, we’ll help you make sure the way it’s invested matches the goal.